Buffalo Spins Registration, Verification and KYC
 Available in GB
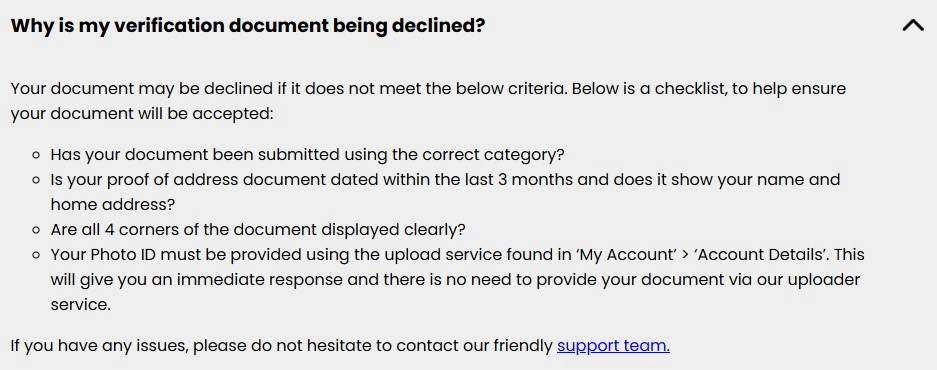
Buffalo Spins can ask for identity, address and payment-method evidence as part of account verification. Its current FAQ lists photo ID, proof of address and proof of payment method, and it asks customers to allow 3 working days for uploaded documents to be reviewed. That is review guidance, not a promise that every account will be fully verified within three working days. The same FAQ also explains that a withdrawal can remain pending when required ID has not been supplied.
The practical point is to treat registration and verification as one account-management process. Use accurate personal details, keep payment methods in your own name, and check the Verification Status area under account details before a withdrawal becomes urgent. Buffalo Spins also sits inside the wider Great Britain regulatory framework, where financial vulnerability checks can be triggered when deposits minus withdrawals exceed £150 over a rolling 30-day period. That regulatory check is separate from Buffalo Spins’ own document-review process.
Table of Contents
- What Buffalo Spins may ask you to verify
- How the upload process works
- What the 3 working-day guidance really means
- Verification and withdrawals are directly connected
- Source of funds is not the same as ordinary KYC
- The £150 financial vulnerability threshold in Great Britain
- Responsible gambling controls available on the account
- Payment details should match the registered customer
- What to do before your first withdrawal
- How this fits with the Buffalo Spins licence
- Preparing for verification before you need a withdrawal
- Sources
- Buffalo Spins verification: prepare before cashing out
- Buffalo Spins Payment Methods and Deposits
What Buffalo Spins may ask you to verify
The official FAQ groups verification into three main categories. First is proof of identity, with a driving licence or passport given as examples. Second is proof of address, such as a utility bill or government-issued letter showing your full name, current postal address and a recent issue date. Third is proof of payment method, such as evidence for a registered payment card showing the cardholder name and the final four digits.
These categories matter because they answer different questions. Identity evidence establishes who controls the account. Address evidence helps confirm where that person lives. Payment-method evidence connects the funding method to the registered customer. Treating them as one interchangeable “KYC document” can create avoidable delays because an accepted identity document does not automatically satisfy address or payment verification.
The FAQ also says the account’s Verification Status section lists the documents required for that specific account and the status of each one. That is more useful than relying on a generic checklist copied from a third-party site. The operator can ask for the categories relevant to the account, and the status screen is the place to see what remains outstanding.
How the upload process works
Buffalo Spins describes different routes depending on the evidence. For photo ID, the FAQ says the Provide link redirects to a secure upload flow and includes a clear photo and selfie step. On desktop, the process can begin with a QR code so the identity flow can continue on a mobile device. For proof of address, the site provides a utility-provider connection option, while an upload option is available when that provider is not listed. Payment-method evidence is submitted through an uploader.
For uploaded documents, the FAQ accepts JPG, PNG and PDF files and asks users to make sure the images are clear. It also tells card users to cover the middle eight digits when providing a card image. Those details are useful because they reduce two common causes of repeat requests: unreadable evidence and overexposure of card data.
What the 3 working-day guidance really means
The FAQ tells customers to allow 3 working days for uploaded documents to be reviewed. The wording is important. It describes how long to allow before chasing the review, not a guaranteed completion deadline for every verification case. A document can still require resubmission if it is unclear, submitted under the wrong category or does not contain the requested details.
The same FAQ has a section explaining why verification documents can be declined. It asks customers to check the submission category, the date and address details on proof of address, and whether all four corners are clearly visible. Photo ID uses the dedicated identity upload service. That makes the best practical strategy straightforward: submit the correct evidence cleanly the first time, then allow the stated review window before contacting support.
Verification and withdrawals are directly connected
Buffalo Spins says a withdrawal can remain pending because ID documents are still required. Its FAQ also says that, for a verified account, a withdrawal begins with a 72-hour pending period and then funds should arrive within 1-3 working days. The withdrawal process covers the timing detail and the separate wording found in the operator’s terms.
For an account-management page, the main lesson is simpler: do not wait until after requesting a withdrawal to discover that the Verification Status section is incomplete. If the site is already asking for evidence, completing that request in advance reduces the chance that verification becomes the reason a cash-out remains pending.
Source of funds is not the same as ordinary KYC
Identity verification answers who you are. Source-of-funds and affordability reviews concern the financial context of gambling activity, so they should not be treated as an extension of the ordinary photo-ID checklist. Buffalo Spins’ current FAQ separately says that a customer asking to increase deposit limits should provide a recent payslip and a recent bank statement. That is evidence for the deposit-limit review described in the FAQ, not a universal source-of-funds checklist for every account.
That distinction matters. A passport proves identity, but it does not explain where gambling funds come from. A bank statement can contain financial information, but its purpose depends on the request being made. If Buffalo Spins asks for additional financial information, follow the request shown on the account rather than assuming that a generic online checklist will satisfy it.
There is also no useful reason to treat a source-of-funds request as something to work around. The correct approach is to provide genuine, relevant documents through the operator’s stated channel; affordability, financial-risk and source-of-funds checks should not be bypassed.
The £150 financial vulnerability threshold in Great Britain
The Gambling Commission’s current Social Responsibility Code requires financial vulnerability checks when a customer’s deposits minus withdrawals exceed £150 in a rolling 30-day period. This threshold has applied since 28 February 2025. The check uses customer-specific public-record information for significant indicators of potential financial vulnerability.
This is a regulator-wide requirement for the relevant remote licences, not a Buffalo Spins-specific “KYC trigger” and not a statement that a player has done anything wrong. It should not be confused with the operator asking for identity evidence, proof of address or payment verification. One process checks account identity and ownership evidence; the other is part of the wider customer-protection framework applied to licensed remote gambling in Great Britain.
The difference also explains why a customer can have a verified identity and still encounter another form of financial check later. Passing one control does not mean every other regulatory or account review disappears permanently.
Responsible gambling controls available on the account
The Buffalo Spins FAQ lists deposit limits, take-a-break and self-exclusion tools. It says these controls are available through the responsible gambling area and can be applied without waiting for customer support. The FAQ also states that applying a safer gambling tool such as a break does not affect the account balance or the ability to be verified.
These controls are relevant to registration and KYC because they sit in the same broader account-management picture. Verification is about establishing and maintaining a valid account relationship. Safer gambling controls are about limiting or stopping activity when needed. They should be treated as separate functions rather than as penalties linked to document review.
Payment details should match the registered customer
The payments FAQ states that payment methods must be owned by, or be in the same name as, the person registered on Buffalo Spins. This is one reason consistent account information matters from the beginning. A mismatch between the registered identity and a payment method creates a predictable verification problem.
For the full list of current deposit methods, GBP rules and the minimum deposit, see the deposits and payments. The key account-level point is that using another person’s card or payment account is not a shortcut around verification. It conflicts with the operator’s stated payment ownership rule.
What to do before your first withdrawal
- Open Account Details and check the Verification Status area.
- Complete any requested identity, address or payment-method steps using the site’s own upload route.
- Check that uploaded files are clear and in an accepted format.
- Allow the stated 3 working days for uploaded-document review before chasing support.
- Keep payment methods in the same name as the registered account holder.
- Read the current withdrawal instructions before assuming the cash-out timer has started.
This sequence is more useful than asking whether Buffalo Spins “does KYC” in the abstract. The answer is yes, but the practical issue is whether your account has an outstanding request and whether the evidence has been submitted in the form the operator expects.
How this fits with the Buffalo Spins licence
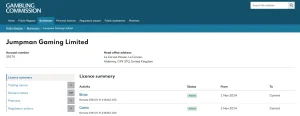
Buffalo Spins is operated by Jumpman Gaming Limited. The current Gambling Commission public register shows account 39175 with active Remote Casino and Remote Bingo permissions, and it lists buffalospins.com as an active domain. The licence and regulation explains what that register evidence proves and the important distinction between Great Britain and Northern Ireland.
For KYC, the main point is that verification is not an isolated website preference. Identity controls, customer-protection requirements and financial checks sit inside the compliance framework that applies to licensed remote gambling in Great Britain. That does not make every individual request identical, so the account’s live Verification Status remains the most relevant place to see what Buffalo Spins wants from you.
Preparing for verification before you need a withdrawal
Prepare for Buffalo Spins verification by expecting three core evidence categories: photo ID, proof of address and proof of payment method. Use the account’s Verification Status page as the live checklist, submit clear files through the instructed route and treat the stated 3 working days as review guidance rather than a guaranteed completion time. If a withdrawal is pending because documents are outstanding, completing verification is part of resolving the delay.
Keep the separate layers clear: basic KYC confirms identity and account details; payment verification confirms ownership of a funding method; further financial checks address a different risk question; and the £150 rolling-30-day vulnerability threshold is a Great Britain regulatory requirement rather than a Buffalo Spins-only rule. For a wider overview of the operator, offers, games and account experience, return to the main Buffalo Spins review.
Sources
- Buffalo Spins FAQ – current verification categories, upload guidance, review timing, withdrawal linkage and safer gambling tools.
- Gambling Commission financial vulnerability check condition – current £150 rolling-30-day threshold.
Buffalo Spins verification: prepare before cashing out
Buffalo Spins can ask for photo ID, proof of address and proof of payment method, and its current guidance asks customers to allow three working days for uploaded documents to be reviewed rather than promising that every check will finish inside that period. Those checks serve different purposes from source-of-funds review, where bank statements, payslips or other affordability evidence can be relevant, and they are also separate from the Great Britain financial-vulnerability framework.
Because a withdrawal can remain pending when required identification has not been supplied, the most practical step is to keep account details accurate and prepare readable documents before a cashout becomes urgent. That preparation does not guarantee an approval time, but it does reduce avoidable mismatches between the registered customer, payment method and documents when Buffalo Spins asks the account to be verified. Keeping the payment method in the same registered name and responding to requests through the official account area also makes it easier to separate routine identity checks from any later source-of-funds review.